If You Never Have Money Left Over, Read This
Disclosure: Some of the links in this post are affiliate links. This means if you click on the link and purchase an item, I will receive an affiliate commission at no extra cost to you.
Reaching the end of the month with zero dollars in your bank account is an exhausting way to live. You work hard every single week, yet your hard-earned paycheck seems to vanish almost instantly. Bills, groceries, subscriptions, and random emergency expenses swallow every single dollar you make.
Many people assume that running out of money stems strictly from not earning a high enough income. However, high earners frequently experience empty bank accounts at the end of the month as well.
In fact, income level matters far less than the daily financial systems you operate within your home.
When you feel stuck in a continuous cycle of living paycheck to paycheck, drastic changes feel scary. Fortunately, regaining control of your money does not require extreme sacrifice or living on plain rice.
Reading this comprehensive guide will help you fix hidden cash flow leaks and build permanent financial freedom.
Understanding the Paycheck-to-Paycheck Trap
The Psychology of Parkinson’s Law in Personal Finance
Parkinson’s Law states that demand expands to match the total supply available for its consumption. In personal finance, this means your spending naturally expands to consume your entire monthly income level.
When you earn a raise, your lifestyle quietly upgrades to absorb every new dollar immediately. Consequently, earning more money rarely solves financial stress without intentional spending boundaries in place.
You end up buying slightly nicer groceries, upgrading subscriptions, and taking more expensive weekend trips.
Breaking this cycle requires interrupting the natural urge to spend whatever sits in your checking account.
Why Budgeting Usually Fails Most People
Traditional budgeting asks you to track every single penny in complex spreadsheets after spending occurs. This reactive approach forces you to log transactions continuously, creating immense mental fatigue and frustration.
When an unexpected expense pops up, your entire rigid budget breaks, causing you to give up completely.
Instead of tracking past failures, successful money management requires proactive forward planning and automated systems.
You need a simple, low-friction structure that directs your money automatically before you ever spend it. Building ease into your financial systems guarantees long-term success without daily stress.
Build an easy, sustainable spending plan by reading How to Build a Family Budget You’ll Actually Stick To.
Identify harmful financial patterns by studying Money Habits That Keep Families Broke.
Uncovering the Invisible Financial Leaks in Your Household
The Hidden Cost of Micro-Transactions and Daily Drips
Single small purchases rarely feel dangerous to your overall monthly bank balance in the moment. A five-dollar morning latte, a quick convenience store snack, or a cheap phone app purchase seem harmless.
However, when repeated daily, these tiny micro-transactions accumulate into hundreds of dollars in hidden monthly leaks.
Furthermore, digital payment methods make spending completely frictionless, removing the psychological pain of handing over physical cash.
To fix these leaks, audit your recent transaction history specifically looking for small, repetitive charges. You will likely discover significant amounts of money disappearing into mindless convenience purchases.
Phantom Subscriptions and Digital Traps
Unused streaming services, app subscriptions, and gym memberships quietly drain bank accounts across the country every month.
Modern companies design subscription models specifically because consumers forget about recurring auto-renewing payments over time. A ten-dollar monthly fee seems small until you multiply it across six forgotten services year-round.
Sit down with your bank statements and highlight every single recurring automatic payment taking place monthly.
Cancel every service you have not used within the past thirty days without hesitation. You can always re-subscribe later if you truly miss a specific platform or tool.
Avoid common household spending errors by exploring 25 Money Mistakes Stay-at-Home Moms Make Without Knowing It.
Shift 1: Reversing the “Pay-Yourself-First” Equation
Why Traditional Saving Equations Always Fail
Most people manage money using an outdated, flawed equation: Income minus Expenses equals Savings. They pay bills, purchase groceries, buy items they want, and hope money remains at month-end to save.
Unfortunately, because human spending expands naturally, there is almost never any money left over using this approach.
To build wealth, you must reverse this equation completely: Income minus Savings equals Expenses. The second your paycheck hits your bank account, transfer a fixed percentage into savings immediately.
You then force yourself to live strictly on the remaining balance left in your checking account.
Automating Your Savings Before You Touch It
Relying on daily willpower to move money into savings accounts is a guaranteed recipe for failure. Human willpower fluctuates based on stress, fatigue, and emotional triggers throughout any given week.
Automation removes human emotion and temptation from your long-term saving strategy entirely.
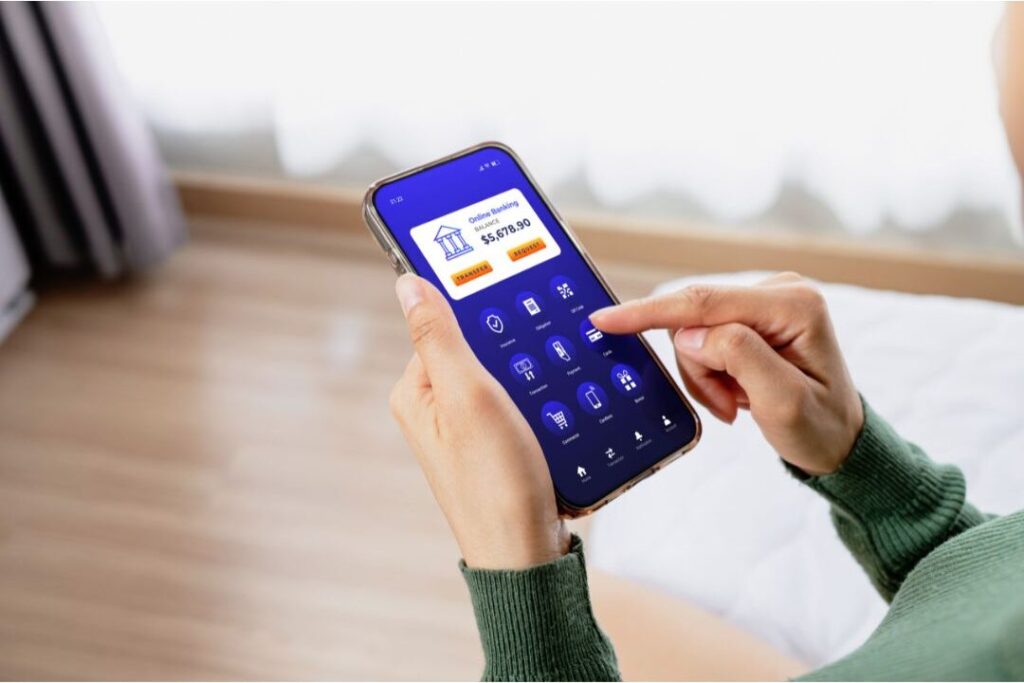
Set up automatic recurring transfers through your bank’s digital app for every single payday. Have money moved automatically into a high-yield savings account before you even see it available.
What remains in your checking account becomes your true spending baseline for monthly living expenses.
Simplify your routines by applying This One Weekly Habit Eliminated So Much Stress.
Shift 2: Auditing Your True Fixed Expenses vs. Variable Wants
The “Essential Need” Illusion
Many people classify almost all of their monthly purchases as non-negotiable fixed living expenses. Premium cable packages, organic brand-name groceries, upgraded phone plans, and frequent hair salon visits feel essential over time.
However, confusing luxury upgrades with core survival needs severely constricts your monthly cash flow flexibility.
Take time to separate your expenses into true survival needs versus comfortable lifestyle choices. True needs consist strictly of basic housing, basic utilities, simple food, essential transportation, and core medications.
Recognizing the difference gives you immediate power to trim expenses whenever cash flow gets tight.
Negotiating Recurring Monthly Overhead
Most consumers accept monthly service bills as fixed, permanent prices that cannot ever be changed or lowered. In reality, internet providers, insurance companies, and mobile carriers compete aggressively for customer retention daily.
A single afternoon spent making phone calls can lower your fixed monthly overhead significantly.
Call your service providers and politely request better promotional rates or lower tier service plans. Mention competitor pricing to give providers a strong incentive to offer you immediate monthly discounts.
Consequently, you can save hundreds of dollars annually without sacrificing your core daily services.
Lower your weekly food expenses drastically using How We Cut Our Grocery Bill in Half.
Shift 3: Changing Your Financial Psychology and Spending Triggers
Identifying Emotional Spending Traps
Spending money is frequently an emotional response to stress, boredom, loneliness, or daily exhaustion. After a long, frustrating workday, ordering expensive takeout or browsing online shopping stores offers instant comfort.
Retail therapy provides a temporary surge of dopamine, followed quickly by financial regret and anxiety later.
To curb emotional spending, identify the specific emotional triggers that drive you to shop or spend. Find free, healthy alternative activities to process negative emotions, such as walking outdoors or reading books.
Replacing retail therapy with restorative self-care protects both your mental health and bank balance.
Implementing the 48-Hour Pause Rule
Impulse purchases kill financial momentum because they bypass your brain’s rational decision-making centers entirely.
Marketers spend billions designing online checkout flows that encourage immediate, unthinking purchase clicks. Implementing a mandatory 48-hour pause rule breaks impulse buying habits effectively and effortlessly.
Whenever you want to buy a non-essential item online, place it in your cart and step away for two full days.
If you still want and need the item after 48 hours, reconsider buying it within your budget. Most times, the initial impulse fades, and you will gladly delete the item altogether.
Reduce spending tension by reading this- Stop Buying These Things – They’re Keeping You Broke
Shift 4: Restructuring Your Banking Systems for Built-in Discipline
The 4-Account Banking Strategy
Keeping all your money inside one single checking account creates financial confusion and constant overspending risks.
When you see a large balance, your brain assumes you have plenty of spending money available. Restructuring your bank layout into four distinct accounts creates natural visual boundaries around your funds:
- Income Checking Account: Where your paycheck lands initially before automated distribution occurs.
- Fixed Bills Checking Account: Dedicated strictly to paying rent, mortgage, utilities, and debt payments.
- Emergency High-Yield Savings Account: Protected funds reserved strictly for true unplanned medical or home emergencies.
- Guilt-Free Spending Account: A separate debit card loaded with leftover fun money for discretionary purchases.
Using distinct accounts prevents you from accidentally spending money reserved for important upcoming bill payments.
Eliminating Credit Card Dependency for Survival
Using credit cards to bridge the monthly gap between income and expenses compounds financial problems exponentially over time.
High credit card interest rates guarantee that past purchases become increasingly expensive every single month. You end up paying interest on last month’s groceries while struggling to afford this month’s food.
To break this cycle, remove credit cards from your wallet and digital auto-fill shopping browsers immediately.
Switch to using cash or debit cards for all daily variable purchases until your cash flow stabilizes. Spending real money forces you to feel the immediate physical reality of every transaction.
Cultivate calm financial management by reading The Hidden Expenses Quietly Destroying Your Budget
Shift 5: Building an Initial Emergency Buffer
Why a $1,000 Buffer Changes Everything
Without cash savings, every minor unexpected event turns into a major financial crisis that causes debt.
A flat tire, minor plumbing repair, or unexpected vet visit forces you to rely on high-interest credit cards. Consequently, you sink deeper into financial stress every time normal life events happen unexpectedly.
Building a starter emergency fund of $1,000 provides an immediate safety buffer against life’s minor surprises.
This money acts as financial shock absorbers, keeping your monthly routine peaceful whenever unexpected costs arise. Knowing you have cash reserves instantly eliminates a massive amount of daily background anxiety.
Where to Find Your First $1,000 Quickly
Finding an extra $1,000 when you feel completely broke seems impossible at first glance. However, most households sit on top of hundreds of dollars in unused physical possessions and hidden savings.
You can accumulate your emergency fund quickly by taking immediate, focused action over a few weeks:
- Sell Unused Items: List old electronics, furniture, clothing, and exercise gear on local digital marketplaces.
- Pause All Subscriptions: Temporarily cancel every non-essential subscription service for sixty days.
- Execute a No-Spend Challenge: Freeze all non-essential discretionary purchases for two consecutive weeks.
- Redirect Tax Refunds or Bonuses: Put unexpected windfalls directly into emergency savings before spending anything.
Uncover environmental stressors with The Decor Mistakes That Make Homes Look Cluttered
Shift 6: Increasing Your Cash Flow Gap
The Power of Capping Your Lifestyle Baseline
Creating a surplus requires widening the gap between what you earn and what you consume monthly. While cutting expenses has a physical limit, capping your lifestyle baseline locks in financial progress permanently.
Whenever you receive a raise, tax refund, or side income, freeze your current living expenses.
Direct one hundred percent of any new income straight into savings, debt payoff, or long-term investments. By keeping your living expenses flat while your income grows, you build massive cash flow rapidly.
Exploring Short-Term Income Boosts
If you have cut your expenses to the bone and still lack cash flow, you face an income problem. Trimming expenses saves money, but scaling your income offers unlimited financial growth potential over time.
Exploring short-term income opportunities can help you break out of financial stagnation much faster.
Consider taking on freelance projects, selling services online, or working temporary overtime hours at work.
Direct all extra income generated exclusively toward debt payoff or building your permanent emergency cash cushion.
Elevate your home experience affordably by learning Luxury Habits Anyone Can Afford
Maintain domestic order effortlessly – Stop Wasting Money On These Household Items
Step-by-Step 30-Day Cash Flow Reset Plan
Week 1: The Full Financial Reality Audit
The first week of your financial transformation focuses entirely on gathering raw data without judgment or shame.
Download your bank and credit card statements from the past three months onto your computer or desk. Use colored highlighters to categorize every transaction into fixed needs, variable wants, debt, and subscriptions.
Calculate the exact total of what enters your household versus what exits every single month. Seeing the real numbers clearly eliminates denial and provides a solid starting point for change.
Week 2: Stopping the Leaks and Trimming Overhead
During week two, take direct action to eliminate every unnecessary financial leak uncovered during your audit.
Cancel unused subscription services, call providers to negotiate bills, and establish a strict food shopping list. Challenge yourself to reduce variable grocery and dining spending by twenty percent this week.
Put credit cards away in a safe drawer and switch exclusively to cash or debit cards. You will immediately feel a sense of control as daily spending slows down dramatically.
Week 3: Restructuring Accounts and Automating Savings
Set up your structured multi-account banking framework during the third week of your reset plan. Open a dedicated high-yield savings account if you do not already possess one today.
Configure automatic transfer rules to move savings into your emergency account every single payday.
Route your fixed bill payments through a dedicated bills checking account to prevent accidental spending. Your household financial operations are now running safely on auto-pilot behind the scenes.
Week 4: Establishing Your New Spending Baseline
Use the final week to live comfortably within your newly established spending framework and boundaries.
Track how it feels to have dedicated bill money sitting safely untouched in your bank accounts. Celebrate the quiet peace that comes with knowing your core financial responsibilities are handled.
Evaluate your progress, adjust variable spending categories if necessary, and commit to continuing these systems long term. You have successfully broken the exhausting cycle of living paycheck to paycheck.
Reclaiming Financial Peace and Control
Taking Your First Simple Action Step Today
Transforming your financial life does not require fixing every single money habit overnight. Focus on taking one small, meaningful action step today to build positive momentum in your life.
Cancel one unused subscription, move twenty dollars into savings, or print out your recent bank statement.
Small, consistent choices compound into incredible financial freedom and peace over time. You possess the capability to build a stable, supported, and prosperous financial future starting right now.
Final Thoughts on Cash Flow Freedom
If you never have money left over, read this reminder: your current financial state is temporary.
By building simple automated systems, trimming invisible leaks, and respecting your boundaries, you transform your relationship with money. Embrace the journey of creating lasting stability and peace for your home.
3 Comments